Monday’s paid social review is unusually calm. The campaign has its own page, form, audience branch, and conversion event. The platform can take credit for the result, ROAS is up, and nobody is arguing about where the order came from.
Then the month closes. New-customer contribution has gone nowhere. In a bad version of this story, it has slipped.
That gap does not convict the landing page. It may explain a difficult offer or help customers choose the right product. It does raise a question that is easy to dodge when the reporting looks good: did the business add this step to help someone buy, or to make a sale easier to claim?
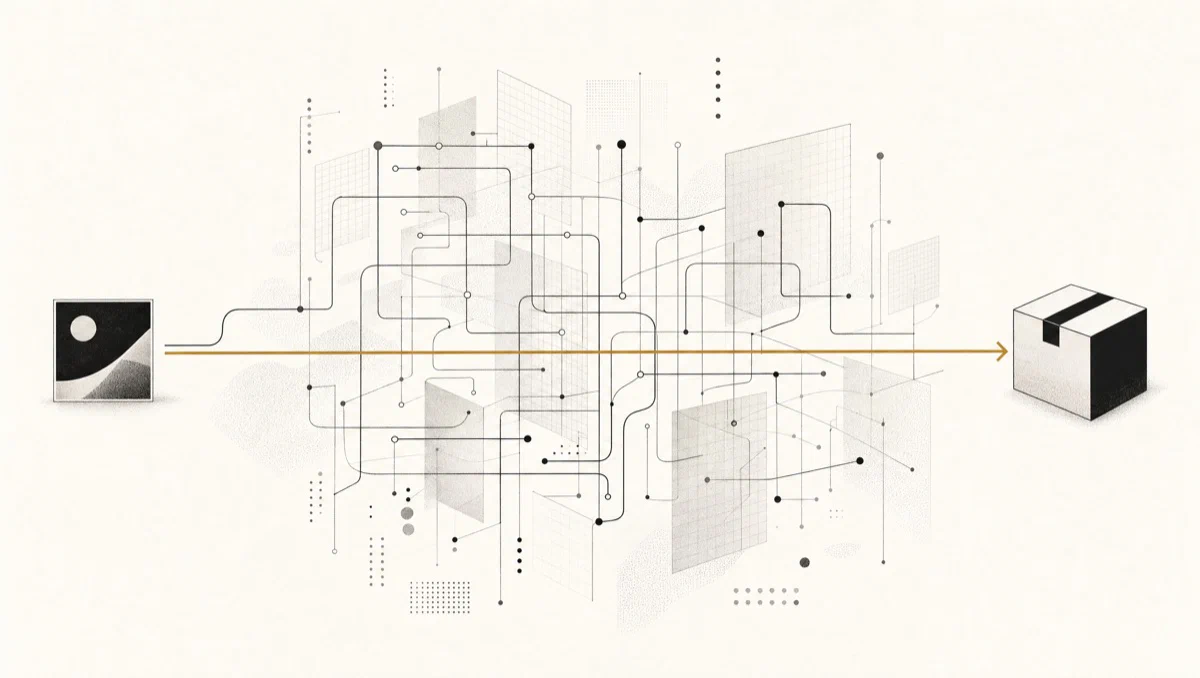
Call that second outcome the Measurement Trap. The business reshapes the buying path to produce attributable events, then mistakes a cleaner report for proof that the change created value.
There is nothing wrong with analytics. The trouble begins when the analytics system gets to write the customer experience. A needless step burns attention, creates work for creative and engineering, and gives somebody a metric to defend. Once taking it away would make the report untidy, it can survive for years without ever making a commercial case.
A path element must earn its place through contribution, customer value, or a necessary operating outcome. Better attribution alone does not clear that bar.
When Measurement Becomes Customer-Path Architecture
Goodhart’s law gives us the first half of the problem: once a measure becomes a target, it can stop doing its job as a measure. Marketers know the pattern. A channel gets tuned toward the event it can report most convincingly, whether that is a click, a lead, or a purchase inside its attribution window.
The Measurement Trap comes next. To keep that event visible, the team starts rebuilding the journey around it. One useful page turns into three channel versions. A voluntary quiz becomes a gate. A discount code exists only to settle a source-of-sale dispute. A customer relationship management (CRM) field remains mandatory because an old report expects it.
The test is not whether the setup feels sophisticated. It is whether it changes the path. Recording a completed purchase usually observes the journey. Putting an email wall between intent and checkout changes it.
That leaves three useful categories:
| Type | What it does | Common examples | What it must prove |
|---|
| Sales architecture | Helps the customer understand, select, trust, buy, or receive value; or satisfies a necessary operating requirement | Product education, an appropriate bundle selector, a required compliance step | Customer, contribution, or operating value |
| Measurement architecture | Exists mainly to create a reportable event, preserve channel credit, or make a system easier to audit | Channel-specific codes, duplicate landing-page branches built only for credit, unnecessary required fields | Incremental commercial value greater than its customer and operating cost |
| Mixed architecture | Serves both a commercial and measurement purpose | A relevant landing page that also creates campaign visibility | Commercial value measured separately from reporting convenience |
This is not a case for tearing down every funnel. A landing page may make a complicated product intelligible. A quiz may produce better product matches. A form may gather consent the business genuinely needs. Each is a claim worth testing.
The warning sign is plainer: “We need it so the channel receives credit.” That can justify a temporary reporting workaround. It does not, by itself, justify a permanent step for every customer.
The Architecture Tax
The report shows its upside immediately. The downside appears later, in places owned by different people: the buying experience, the operating calendar, and the P&L.
1. The customer price
Picture the customer who clicks an ad expecting to see a product and lands in a detour. They have to decide whether this is the right page, whether the form is worth filling out, or how to get back to the item they came for. Most will not send a note explaining why they left.
The damage is quieter. Checkout completion softens. Mobile purchases take longer. Engagement holds up while new-customer orders do not. A short path can fail, too, especially when it strips out product education people need. That is not an argument for minimalism. It is an argument for making each bit of friction earn its job. A cleaner report is not a customer benefit.
2. The operating price
A channel-specific path arrives as a small request. Then it needs a versioned brief, creative, an implementation ticket, a quality check, consent review, and someone to maintain the tracking. Months later, it needs an explanation for why it reports differently from the next path over.
The cost never lands in one budget. Paid media keeps the URLs alive; creative makes variants; development repairs tags; an analyst explains an event change. Leadership burns meeting time reconciling a number that exists only because the journey was split. One branch is rarely the problem. At ten branches, you are running an operating system whether you call it one or not.
Before adding another, ask the unglamorous question: would an experiment, a sample, a post-purchase survey, or a portfolio metric answer this decision well enough?
3. The decision price
The last cost is harder to spot because it feels like progress. A path makes a channel easier to explain. The business may be no better off.
ROAS rises because a campaign can be connected more cleanly to an order. A local conversion rate rises because the team has started counting quiz completions. Neither tells you whether contribution improved after media, fulfillment, discounts, returns, and the labor required to keep the path running.
When paid acquisition is on the line, the order of authority is:
- Contribution profit and new-customer economics: Did the change create more value after the costs that matter?
- Business-level guardrails: Did total revenue, cash, inventory capacity, and customer quality remain healthy?
- Channel diagnostics: What do MER, ROAS, conversion rate, and attribution reports suggest you should investigate next?
Marketing efficiency ratio (MER), total revenue divided by total marketing spend, belongs in the guardrail column. It is not contribution analysis and it will not rescue a bad decision. It is, however, difficult for one channel to improve by quietly changing its own reporting rules. Attribution Triage for Operators shows how to reconcile that portfolio view with channel data.
A simple contribution comparison
The arithmetic is straightforward. Choosing the right outcome is the harder part.
Illustrative scenario: A brand sends 10,000 comparable paid visitors to a product page. The traffic produces 320 orders. Each order contributes $110 after product cost, fulfillment, payment fees, and discounts, but before media. With $20,000 in media cost, the path produces $15,200 in contribution after media, or $1.52 per visitor.
The team replaces that destination with a campaign-specific, measurement-heavy sequence. It produces 295 orders from 10,000 comparable visitors. The order contribution is unchanged, media cost is still $20,000, and the new path requires $1,200 of recurring creative and maintenance work for the campaign period. Contribution after media and path cost is now $11,250, or $1.13 per visitor.
The campaign report from the second path looks tidier. The business has $3,950 less contribution.
The formula to use is:
Contribution profit per visitor =
  (orders × contribution per order − media cost − incremental path cost)
  ÷ visitors
For subscriptions, decide how renewals count before the test starts. A higher-consideration offer may need a downstream qualification or close rate. The formula will vary by business. The discipline stays the same: measure the economic promise the step makes.
Audit the Path Before You Optimize It
Auditing begins with an argument, not a spreadsheet. Draw the entire customer path across all pages on a screen from where the customer saw the ad through to the final order confirmation. Include every page, every form, every line of code, every routing rule, and every CRM field and event gate. Next to each item include when it arrived and what decision it was supposed to help make.
Let’s assume the path looks like this: Meta Ad -> Campaign Page -> Email Form -> Product Page -> Checkout. “The campaign page provides for a better message match,” somebody states. “The form allows the channel to view the lead,” someone else says. Both could be right. As soon as you begin mapping out the process, the group will indicate which claims it is supporting.
It is very boring. Good. It isolates the intentional decisions made by individuals from the machinery that none of them remember approving. Four common explanations tend to show up in the margins: “We had to create a separate page so that Meta could view it.” “The form provides for a cleaner lead source.” “The code enables our partner to capture the sale.” “We cannot delete that field since we need it to do the report.” None of these lines resolves the issue. Instead, they indicate a measurement claim that has a corresponding commercial requirement.
If the team member who initiated the addition of a step is still present, ask what decision the step was intended to help make. Not if the dashboard likes it. What does the customer or the business receive in exchange?
This is the Inventory Test. It generates a map; it is not a purge list.
When you are ready for the next stage, shut down the dashboard and prohibit yourself and others from using five words: track, attribute, report, source, and dashboard. The prohibition may seem arbitrary, but it helps keep the team from providing a reporting benefit instead of a commercial answer to a commercial question. Ask:
What customer, contribution, or required operating value does this step create?
“Better product matching” is an actual hypothesis. “More accurate shipping” is another. “Fewer unqualified sales” is a third. All three can be tested. If the room members cannot determine a specific benefit created by the element, then it may be measurement architecture dressed up in sales-architecture clothes. The Value Test converts reporting-based justifications into commercial claims – or shows the lack thereof.
Prior to anyone seeing results, resolve the question that normally gets put off until the arguments begin. Imagine the test comes back with higher contribution profit and lower channel-attributable ROAS:
If contribution profit and total new-customer economics improved, but this channel’s attributable ROAS fell, which result would govern the decision?
Record the answer in the test memo before the result arrives. If a business-level result cannot override a channel result, then the channel is sovereign. No analytics implementation will solve this problem. The Sovereignty Test indicates whether the business ultimately ranks above or below the tool used to measure performance.
The final question typically reveals the most about a given situation: which experiment would you rather not run due to dirty attribution? Possibly it directs traffic directly to a product page; possibly it eliminates some type of capture step; or maybe it offers an incentive without channel-exclusive codes. Reluctance does not prove that your current design is wasting money. It identifies the section of the journey that has so far avoided commercial scrutiny. This is the Fear Test.
Do not develop an audit maturity score. Leave with a brief list of steps, associated commercial hypotheses, and reasons why they have not been tested yet. Identify the initial step whose business case is primarily still an attribution story. Challenge that one first. Leave everything else alone until you learn something.
Run a Controlled Simplification Test
We are not trying to make the business unquantifiable. The next step is to compare the commercial counterfactual at the decision-making level.
Assume the issue at hand is a campaign landing page. I would include one sentence at the top of the test memo: Does this page produce more contribution than sending the same ad traffic to the corresponding product detail page? Do nothing to the offer, creative, assortment, and checkout. If those also shift, the result may be interesting, but it will not help you understand the page.
A randomized-controlled experiment provides the best practical method to disentangle an experience variation from other factors because assignment to either group by randomization replaces customer self-selection with respect to which version a customer receives. A DTC brand does not require a large testing division; however, a fair comparison and sufficient time to allow the comparison to run are required.
Split eligible visitors into two groups as close to equal as possible using whatever testing tools are available. Maintain audience, spending, creative, offer, inventory position, and dates constant. Record the assigned experience prior to the visitor reaching the page. Next, associate it with the order and its contribution. This represents the bare minimum data needed to address the question.
If randomization is unavailable, a geographic or temporal comparison may provide some insight. Document what could cause confusion. Seasonality, auction changes, inventory availability, and creative fatigue could all be mistaken for a path effect.
The test requires an outcome hierarchy in addition to the above. First select the primary number: contribution profit per visitor, contribution after media, or new-customer contribution based on how the decision is being made. Include several guardrails adjacent to this primary metric, including total revenue, refund percentage, average order value, inventory capacity, service contact requests, and customer quality. Conversion rate, MER (marketing efficiency ratio), channel ROAS (return on ad spend), lead completion, and platform-attributed revenue are useful for diagnosis. They can help explain why a particular version won. However, none of them can override the primary metric.
Develop this hierarchy before running the test. This way, when a preferred version fails on contribution, somebody cannot simply develop a winning slide regarding conversion rate. That is not an honest readout. Conversion rate is valid evidence; it is not a verdict when the paths have different margins, customer mixes, or operating costs.
“10 percent of traffic for four weeks” is a placeholder and does not constitute a test plan. Sample size depends on baseline traffic, conversion rate, order economics, and the smallest difference deemed worth acting on. Establish the decision rule before commencing the test. For example, remove the step if the simplified path produces at least a 5% increase in contribution per visitor without increasing refunds or support contacts. Set a downside limit as well: stop treatment if contribution drops 10% below control after the specified minimum review period. These are examples, not universal thresholds. Establish limits that reflect the operational economics and financial risks the business can absorb.
For the analysis, retain assignment, purchase information, order contribution, and media cost. This is sufficient to determine whether the customer paths earn their costs where decisions are being made. Any touchpoint credits native to platforms may be lost. Acceptable loss. The purpose of conducting the test is to determine whether earning a customer’s dollars merits retaining a path rather than generating additional credit for platforms.
Keep What Creates Contribution, Not What Creates Credit
The results of the test should resolve disputes, not generate additional dashboard debates. If the path lifts contribution, creates value for customers, or maintains essential operating outcomes, it has demonstrated its right to remain as-is and potentially grow. If its principal achievement was merely making reporting easier and no viable business rationale exists for retaining it, simplify it or eliminate it. A middle-ground step gets a third option: preserve customer value but remove the measurement complexity that surrounds it.
Record this choice on the dashboard; do not silently create an alternative choice. Once the test alters a path, update metric definitions, ownership, and the comparability note within the reporting specification. Marketing Dashboard Metrics discusses the governance principles that ensure such updates occur.
A customer journey is not an appendix to a report. Observe with minimal obstruction allowed by the decision. Test elements of a path that alter the experience. Wherever contribution and credit conflict, contribution prevails.
As a practical starting point, identify any path element your team would dislike losing because reporting would become difficult. Develop a single-sentence hypothesis for the customer value created by this element. Create the simplest reasonable test design that could refute it.
Preserve the step if it demonstrates value creation. Remove it if it can demonstrate only ease of reporting for customers and operations.